Are you wondering how much you’ll need to shell out for auto insurance in Massachusetts? You’re not alone. Whether you’re a new driver or a seasoned road warrior moving to the Bay State, understanding the ins and outs of auto insurance costs can feel like deciphering a secret code. But don’t worry—we’ve got you covered!
In this guide, we’ll break down everything you need to know about auto insurance in Massachusetts. From mandatory coverage requirements to the factors that affect your premium, we’ll leave no stone unturned. So, buckle up and let’s dive into the specifics of how much auto insurance can cost you in Massachusetts, and more importantly, how you can save some cash.
Overview of Auto Insurance Requirements in Massachusetts
Did you know that Massachusetts has some of the strictest auto insurance laws in the country? If you’re driving here, you need to know what’s required.
Auto insurance isn’t just a suggestion in Massachusetts—it’s a legal requirement. But what exactly does that mean for you? Let’s dive into the specifics.
Mandatory Auto Insurance Coverage
If you’re hitting the road in Massachusetts, you need to carry a few essential coverages. First up, there’s Bodily Injury to Others, with a minimum limit of $20,000 per person and $40,000 per accident. Then, you’ll need Personal Injury Protection (PIP), set at $8,000 minimum. Massachusetts also mandates Bodily Injury Caused by an Uninsured Auto, with at least $20,000 per person and $40,000 per accident, and Property Damage with a minimum of $5,000.
Penalties for Driving Without Insurance
Think you can skip insurance? Think again. Driving without insurance in Massachusetts can lead to a fine of $500 to $5,000, a one-year license suspension, and even possible jail time. That’s a risk you don’t want to take.
Pro Tip: Always keep proof of your insurance in your car. It can save you from hefty fines and legal headaches.
Factors Affecting Auto Insurance Rates in Massachusetts
Did you know that your age could cost you hundreds more in insurance premiums each year? It’s true! In Massachusetts, several factors play a massive role in determining how much you shell out for auto insurance.
From your age to your driving history and even the type of vehicle you drive, every factor can give your insurance rate a hefty nudge. Let’s break down how each element impacts your premium.
The Impact of Age, Driving Record, and Vehicle Type
Age is not just a number when it comes to insurance. Younger drivers often face sky-high rates due to inexperience, while seasoned drivers see a drop in premiums. BUT, a poor driving record can quickly spike those rates regardless of age. If you’ve collected tickets or caused accidents, expect to pay more.
The vehicle type you drive also makes a difference. Sports cars and luxury vehicles generally cost more to insure because they’re expensive to repair and replace. On the other hand, a reliable sedan or SUV might keep your premiums in check.
Urban vs. Rural Insurance Rates
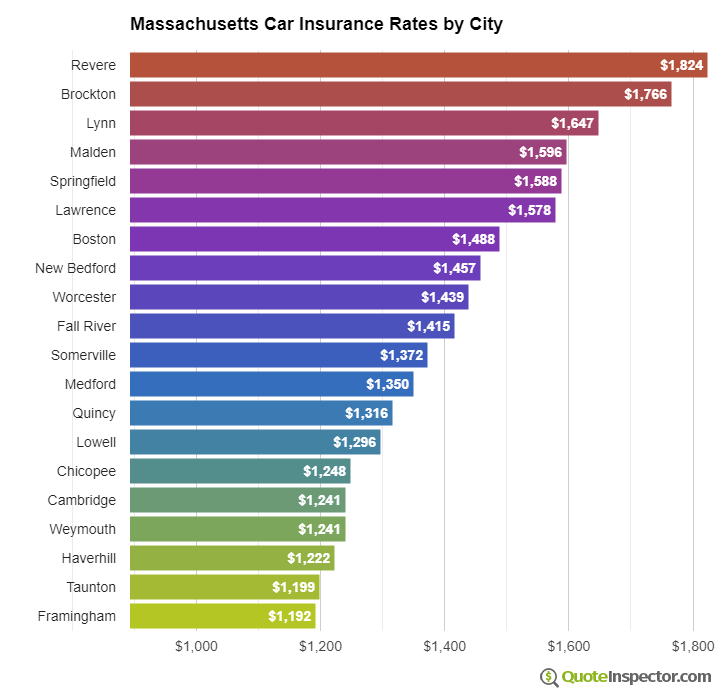
Where you live in Massachusetts can also affect your insurance rate. Urban areas tend to have higher premiums compared to rural regions. More cars, more traffic, and higher crime rates in cities like Boston mean a greater risk for insurers.
| Region | Average Annual Premium |
|---|---|
| Boston (Urban) | $1,500 |
| Springfield (Urban) | $1,350 |
| Amherst (Rural) | $1,100 |
| Great Barrington (Rural) | $1,000 |
Rural areas like Amherst or Great Barrington, with fewer vehicles and less congestion, tend to enjoy lower rates. Here is the deal: where you park your car overnight could save (or cost) you hundreds.
Influence of Credit Score on Insurance Costs
Your credit score can be a silent factor in determining your insurance premium. Insurers often use credit scores as a predictor of risk. A better score usually means a lower premium.
Pro Tip: Boost your credit score to potentially slash your auto insurance costs by hundreds annually.
In Massachusetts, while the influence of credit score is slightly less pronounced than in other states due to regulation, it still matters. Stay on top of your credit health to keep your insurance rates in check.
Average Cost of Auto Insurance in Massachusetts
Did you know that Massachusetts residents pay an average of $1,223 annually for car insurance? That’s right. Your auto insurance could be taking up more of your budget than you think.
But here’s the deal: not everyone pays the same. Your rates depend on factors like age, location, and even your driving record. Let’s dive into how these numbers break down.
Insurance Premiums for Different Demographics
The cost of auto insurance can vary dramatically depending on who you are. For instance, young drivers might pay more than experienced ones.
Here’s a quick breakdown of average annual premiums:
- Teens: $3,750
- 20s: $1,500
- 30s: $1,100
- 40s: $950
- 50s: $890
- 60s: $890
Pro Tip: If you’re under 25, maintaining a clean driving record can significantly lower your rates over time.
Cost Breakdown by Insurance Providers
Choosing the right provider can save you hundreds. Here’s a breakdown of average costs across major insurers:
- Geico: $1,050
- Progressive: $1,200
- State Farm: $1,100
- Liberty Mutual: $1,350
- Allstate: $1,450
Remember, these are averages. Your rate might be different based on your personal circumstances.
Historical Trends in Auto Insurance Costs
Wondering how auto insurance rates have changed over the years in Massachusetts? Here’s a snapshot:
| Year | Average Annual Premium |
|---|---|
| 2013 | $1,100 |
| 2015 | $1,150 |
| 2017 | $1,200 |
| 2019 | $1,275 |
| 2021 | $1,300 |
| 2023 | $1,223 |
As you can see, the past decade has seen a steady climb in rates. But knowing where these numbers come from can help you make smarter choices.
Tips to Lower Auto Insurance Costs in Massachusetts
Shocked by your auto insurance bill? You’re not alone. Many drivers in Massachusetts are paying more than they need to. The good news is, you can cut down those costs significantly.
There are several strategies you can use to lower your auto insurance premiums. And the best part? They’re super easy to implement. Let’s dive into them.
Simple Strategies for Reducing Premiums
One effective way to slash your insurance costs is by bundling your policies. If you have homeowners or renters insurance, see if your provider offers a bundle discount. Another approach is to increase your deductible. Yes, it means more out-of-pocket costs if you have an accident, but it can also mean significantly lower premiums.
Pro Tip: Consider a higher deductible only if you have enough savings to cover it.
Checklist of Available Discounts for Massachusetts Drivers
Ever wondered what discounts you might qualify for? Here’s a quick checklist:
- Safe Driver Discount: Clean driving records can save you a bundle.
- Student Discount: Students with good grades often qualify for lower rates.
- Multi-Vehicle Discount: Have more than one car? Insure them together.
- Low Mileage Discount: Drive less, pay less.
Check with your insurer to see which of these discounts you can take advantage of. Often, you just need to ask.
Comparing Cost-Saving Strategies
Here’s how different strategies stack up in terms of potential savings:
| Strategy | Potential Savings (%) |
|---|---|
| Bundling Policies | 5-15% |
| Increasing Deductibles | 10-30% |
| Safe Driver Discount | Up to 20% |
| Student Discount | Up to 25% |
Adjust your insurance strategy using the table above for maximum savings. Each percentage point saved is more money in your pocket.
Top Auto Insurance Providers in Massachusetts
Ever wondered which auto insurance company is the top dog in Massachusetts? With dozens of options available, picking the right one can be a game-changer for your wallet and peace of mind.
In Massachusetts, the auto insurance market is competitive, with companies vying to offer the best rates and services. Customer satisfaction, unique features, and efficient claims processing are key factors that set the best providers apart from the rest.
Leading Insurance Companies Based on Customer Satisfaction
When it comes to customer satisfaction, not all insurance companies are created equal. According to the latest surveys, these are the top options:
- Liberty Mutual: Known for its customizable coverage options and competitive rates, Liberty Mutual is a favorite among Massachusetts drivers. Their 24/7 claims assistance is also a big plus.
- Amica Mutual: This company consistently ranks high for customer satisfaction, thanks to its stellar customer service and comprehensive coverage options. They’ve been around for over a century, proving their reliability.
- USAA: While only available to military members and their families, USAA is often praised for its excellent customer service and value-packed policies.
Unique Features and Benefits of Each Provider
Each top provider offers something unique, giving them an edge in the competitive Massachusetts market. Here’s the deal:
- Liberty Mutual: Offers accident forgiveness and a “Better Car Replacement” program, which can replace your totaled car with one a year newer.
- Amica Mutual: Provides a dividend policy option where customers can receive a portion of their premiums back.
- USAA: Offers additional benefits like roadside assistance and rental car reimbursement, making them a comprehensive choice.
The Role of Customer Service and Claims Processing
Here’s the truth: a seemingly small detail like customer service can impact your entire insurance experience. Efficient claims processing is essential when you’re in a jam.
Look for companies with high claims satisfaction ratings. A smooth claims process can save you a lot of stress. Pro Tip:
Always read customer reviews and ask about claims satisfaction rates before choosing a provider.
The Claim Process for Auto Insurance in Massachusetts
Ever wondered why some insurance claims get processed faster than others? It’s all about knowing the system. Let’s break down how to file an auto insurance claim in Massachusetts so you can get back on the road ASAP.
Filing an auto insurance claim in Massachusetts may seem daunting, but it doesn’t have to be. Follow these clear steps to ensure a smooth process. From gathering necessary documentation to final resolution, understanding each phase is crucial.
Step-by-Step Guide to Filing an Auto Insurance Claim
First things first: after an accident, contact your insurance provider immediately. This sets the wheels in motion for your claim. You’ll need to provide details about the accident, including time, location, and who was involved.
Next, your insurance company will assign a claims adjuster to your case. They evaluate the damage and determine how much you’ll receive. But here’s the deal: make sure to document everything.
- Report the accident to your insurance company.
- Document the scene with photos and gather witness information.
- Get a police report to substantiate your claim.
- Work with your claims adjuster to assess damages.
- Follow up regularly to ensure a timely resolution.
If you’re proactive and stay organized, the typical timeline from filing to resolution is about 30 days, although it can vary based on complexity.
Documentation Required for a Successful Claim
Without the right documentation, your claim might hit roadblocks. You’ll need a police report, photos of the damage, and any medical records if injuries were involved. The more comprehensive your records, the smoother the process.
Pro Tip: Keep a dedicated folder for all claim-related documents. This makes it easy to provide everything your insurer needs without delay.
Also, don’t forget receipts for any towing or repair costs. These can be reimbursed if they’re part of your policy.
Final Summary
By now, you should have a firm grasp on the intricacies of auto insurance in Massachusetts. While the costs can vary greatly depending on a multitude of factors, being informed is your first step toward securing a deal that won’t break the bank. Remember, shopping around and understanding your options can lead to significant savings. Safe travels, and may your insurance premiums always be in your favor!
Common Queries
What are the minimum auto insurance requirements in Massachusetts?
In Massachusetts, drivers are required to have minimum coverage of $20,000 per person and $40,000 per accident for bodily injury, along with $5,000 for property damage.
How does my age affect auto insurance rates in Massachusetts?
Younger drivers, particularly those under the age of 25, often face higher premiums due to perceived risk factors associated with inexperience.
Are there penalties for driving without insurance in Massachusetts?
Yes, driving without insurance can result in fines, license suspension, and potential legal action. It’s not worth the risk!
Can my credit score impact my insurance costs?
Absolutely. In Massachusetts, a good credit score can lead to lower insurance premiums, while a poor score might increase your costs.
How can I lower my auto insurance premiums?
Consider bundling your policies, maintaining a clean driving record, taking advantage of discounts, and reviewing your coverage annually to ensure you’re getting the best rate.
