If you’re on the hunt for the best insurance rates in NC, you’ve come to the right place. North Carolina’s insurance landscape can be as diverse as its beautiful coastal views and mountainous terrains. Whether you’re a resident or planning to move to the Tar Heel State, understanding the ins and outs of insurance rates here is crucial. Let’s embark on a journey to navigate through the top insurance providers, what makes them special, and how you can snag the best deals without breaking a sweat.
At Backlinko, we believe in empowering readers with the latest and most relevant insights. So, buckle up as we dive deep into the factors influencing insurance rates in North Carolina, explore affordable options, and stay ahead of future trends. From customer satisfaction scores to government programs that offer support, we’ve got all the juicy details you need to make informed decisions.
Exploring the Best Insurance Providers in North Carolina
Did you know that nearly 15% of NC residents shop for new insurance every year? That’s a lot of people searching for the best deals. But how do you find the right provider for your needs?
Let’s dive into the top insurance companies in North Carolina, analyze their offerings, and see what makes them stand out. With so many options, understanding what makes an insurer unique can help you make an informed decision.
Top North Carolina Insurance Companies and Their Offerings
When it comes to insurance in North Carolina, three names often come up: State Farm, Nationwide, and Blue Cross Blue Shield. Each offers a range of products from auto to health insurance, but they excel in different areas.
- State Farm: Known for its personalized service and comprehensive auto insurance options.
- Nationwide: Offers competitive rates for homeowners and has strong customer service ratings.
- Blue Cross Blue Shield: The go-to for health insurance with extensive coverage options.
But here’s the deal: It’s not just about the offerings. The level of customer satisfaction and the company’s reputation play a huge role in choosing the right provider.
Comparing Customer Ratings
Customer ratings can be a real eye-opener. They not only reflect the quality of the service but also the company’s ability to handle claims. JD Power’s 2023 U.S. Insurance Study highlights State Farm as the leader in customer satisfaction, followed by Nationwide.
These ratings are a crucial factor to consider. Why? Because how a company treats its customers during a claim can make or break the insurance experience.
Key Factors That Make an Insurance Provider Stand Out in NC
What sets apart an average insurance provider from the best? It’s all about coverage options, customer service, and pricing.
Pro Tip: Look for insurers that offer bundling discounts—combining policies can save you a bundle!
State Farm and Nationwide are known for their excellent customer service and competitive pricing, while Blue Cross Blue Shield stands out for its extensive network of healthcare providers.
Insurance Companies, Unique Features, and Customer Satisfaction Scores
Here’s a quick comparison of the top providers in NC:
| Company | Unique Features | Customer Satisfaction Score |
|---|---|---|
| State Farm | Excellent auto insurance, personalized service | 4.5/5 |
| Nationwide | Strong customer service, homeowners discounts | 4.3/5 |
| Blue Cross Blue Shield | Extensive healthcare network, comprehensive coverage | 4.4/5 |
Choosing the right insurance provider in North Carolina can be daunting, but armed with the right information, you can make a smart choice that fits your needs.
Factors Affecting Insurance Rates in North Carolina
Ever wonder why your insurance rates are higher than your neighbor’s? It’s not just about your driving record. There are multiple factors at play.
North Carolina’s insurance rates are influenced by a mix of geographical, personal, and state-specific factors. Understanding these can help you get the best deal possible.
The Impact of Location on Your Premium
Did you know that where you live in North Carolina can significantly impact your insurance rates? Urban areas like Charlotte or Raleigh tend to have higher premiums due to increased traffic and accident rates. On the other hand, rural areas often benefit from lower rates because of less congestion.
Insurance companies assess key factors such as crime rates, weather patterns, and proximity to medical facilities. Here is the deal: living in a region prone to hurricanes or theft can deter insurers and inflate your costs.
Personal Factors and Their Influence
Your personal profile is a critical component in determining insurance rates. Credit scores are a major player here. A higher score can unlock better rates, while lower scores might push costs up. Why? Insurers believe that credit history reflects your likelihood to file claims.
Besides credit, your age, marital status, and even your vehicle’s make and model are part of the equation. Younger drivers or those with sports cars often face steeper rates as they are perceived as higher risk.
Pro Tip: Regularly check your credit report for errors and work on improving it to enjoy lower insurance premiums.
| Factor | Effect on Rates |
|---|---|
| Urban vs Rural Location | Urban areas tend to have higher rates |
| Credit Score | Higher scores can result in lower premiums |
| Age | Younger drivers typically pay more |
| Vehicle Type | Luxury and sports cars may increase rates |
Affordable Insurance Options in NC
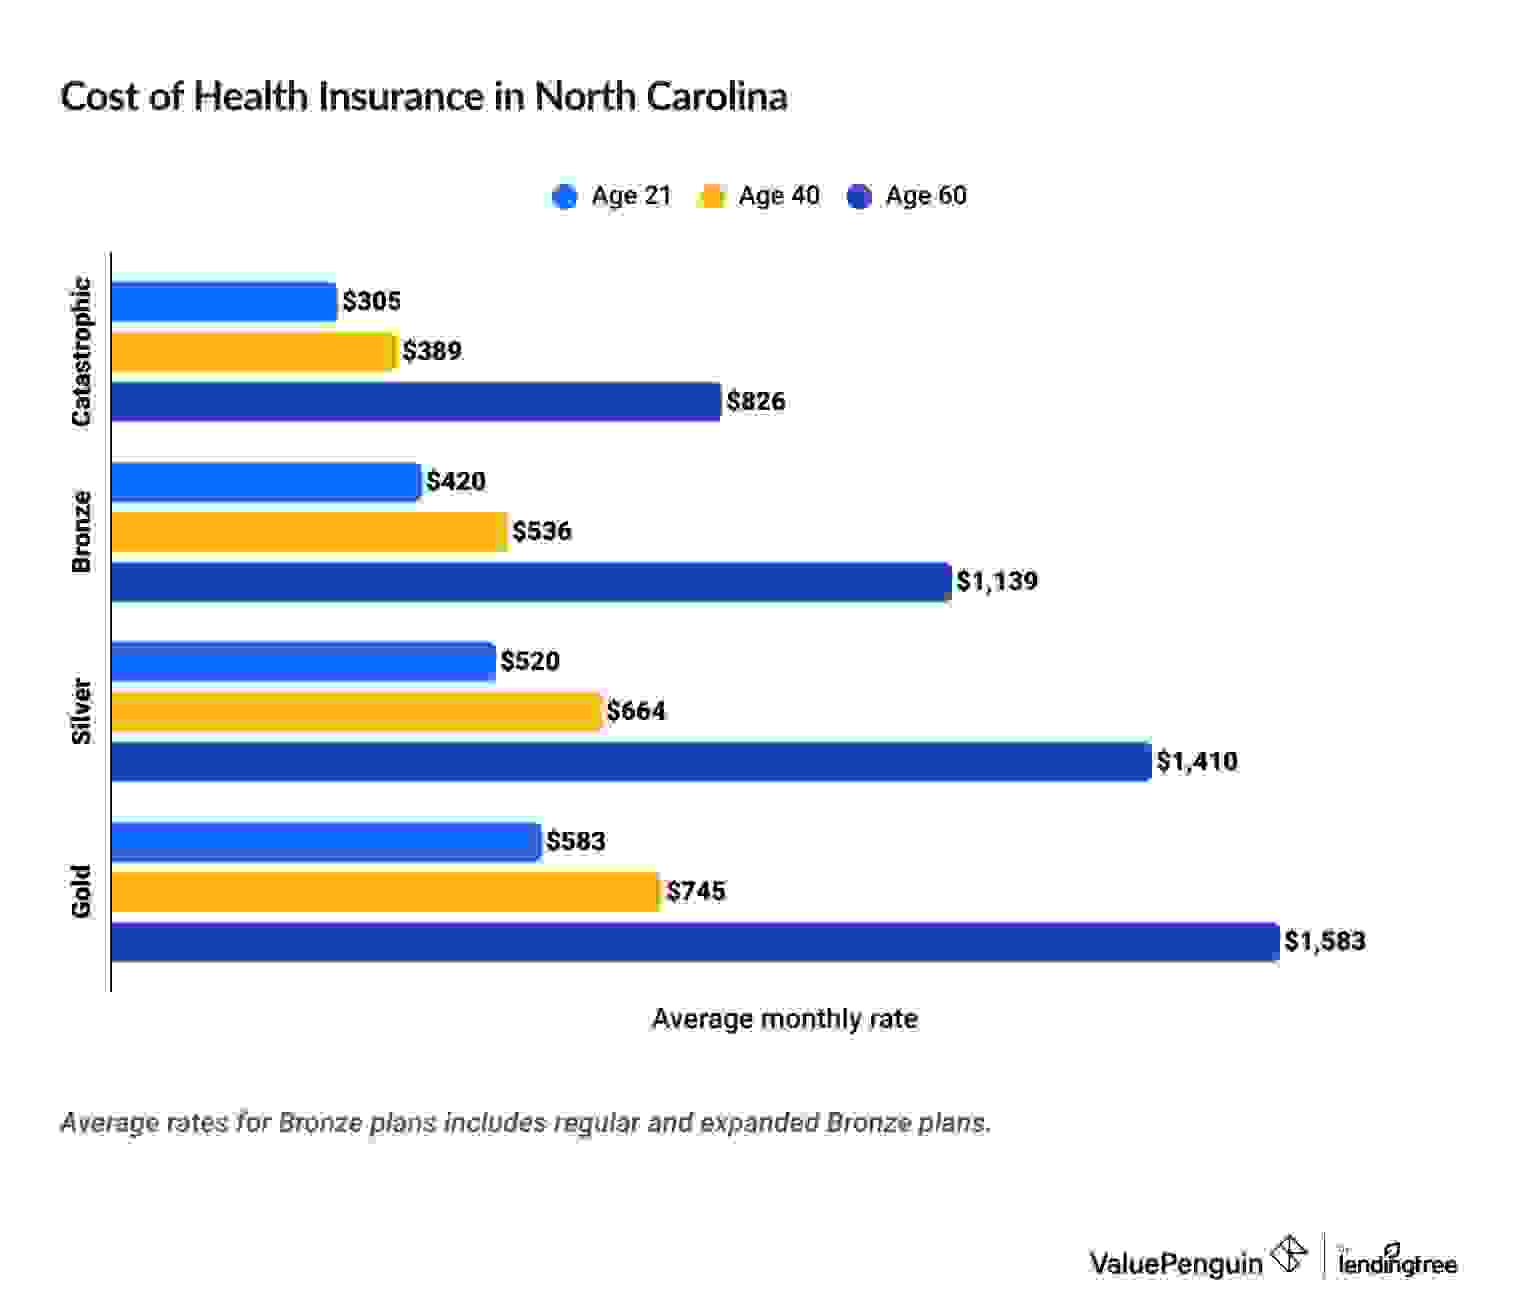
Finding affordable insurance in North Carolina can seem like searching for a needle in a haystack. But with the right strategies, you can score excellent coverage without breaking the bank.
Did you know that North Carolina has some of the most competitive insurance rates in the country? Yet, many residents still overpay. Here is the deal: if you want to save money, you need to leverage discounts and special programs.
Strategies for Finding Affordable Insurance Rates in NC
The first step to unlocking affordable insurance in NC is comparison shopping. Don’t settle for the first quote you get. Comparing quotes from multiple providers can save you hundreds, if not thousands, annually.
Another key strategy is to raise your deductible. Yes, you’ll pay more out of pocket in the event of a claim, but your monthly premiums will be significantly lower. This approach can be a game-changer for those who rarely file claims.
Bundling your insurance policies can also lead to substantial savings. Many companies offer discounts if you bundle home and auto insurance together.
Examples of Discounts Available from NC Insurance Providers
Insurance companies in NC offer various discounts that can dramatically reduce your premium. Here are some you might want to explore:
- Safe driver discounts for those with a clean driving record
- Military discounts for active and retired personnel
- Multi-policy discounts for bundling your insurance policies
- Good student discounts for young drivers with strong academic performance
- Anti-theft device discounts for installing approved security systems in your vehicle
Pro Tip: Always ask your insurance agent about hidden discounts. Many people miss out simply because they don’t inquire.
Government Programs Offering Insurance Support in NC
Not everyone knows about the government programs available to help lower insurance costs in NC. The state’s Fair Plan is designed to provide insurance for those who can’t find coverage elsewhere due to high-risk factors.
Additionally, North Carolina offers a Health Insurance Marketplace to aid residents in selecting subsidized health insurance plans. It’s especially beneficial for low-income individuals and families.
Cost-Saving Tips for NC Residents
Implement these tips to reduce your insurance costs substantially:
- Regularly review and update your insurance coverage to eliminate unnecessary options.
- Improve your credit score, as insurers often use it to determine your rates.
- Install safety features in your home and vehicle to qualify for additional discounts.
- Participate in a defensive driving course to potentially lower your auto insurance premium.
- Pay your premium annually instead of monthly to avoid installment fees.
Comparing Insurance Policies in NC
Did you know that North Carolina has some of the most varied insurance options in the country? If you’re shopping for insurance here, you need to know exactly what you’re getting into.
Insurance policies can be confusing with all their terms and conditions. But you don’t have to be an expert to make a smart choice. Let’s break down the different types of insurance policies available in North Carolina.
Policy Types Available in North Carolina
North Carolina offers a range of insurance policies tailored to different needs. You can choose from basic liability policies to full coverage plans that include comprehensive and collision coverage.
- Liability Insurance: Covers damages you cause to others. It’s the minimum required by law.
- Full Coverage: Includes liability, but also covers your vehicle in case of an accident, theft, or weather damage.
- Uninsured/Underinsured Motorist Coverage: Protects you if the other driver doesn’t have enough insurance.
Pros and Cons of Different Insurance Policies
Each insurance policy type has its upsides and downsides. Here’s the deal:
- Liability Insurance: Pros: Cheapest option, legal requirement met. Cons: Doesn’t cover your own car.
- Full Coverage: Pros: Comprehensive protection, peace of mind. Cons: Higher premiums.
- Uninsured/Underinsured Motorist: Pros: Extra security. Cons: Additional cost.
Pro Tip: Always consider adding uninsured motorist coverage. It’s a small price for big protection.
Differences Between Full Coverage and Liability Insurance
If you’re wondering whether to choose full coverage or stick with liability insurance, it boils down to your personal situation and comfort with risk. Full coverage is ideal if you drive a newer car or want comprehensive protection. But, liability might suffice if you’re driving an older car and looking to save on premiums.
Insurance Policy Comparison Table
Here’s a quick comparison to see how these policies stack up in terms of coverage limits and premiums:
| Policy Type | Coverage Limits | Premiums |
|---|---|---|
| Liability Insurance | $30,000/$60,000/$25,000 | Low |
| Full Coverage | Comprehensive + Collision | High |
| Uninsured/Underinsured Motorist | Matches Liability Coverage | Moderate |
By understanding these options, you can make an informed decision that suits your needs and budget.
Understanding Insurance Regulations in North Carolina
Did you know that North Carolina has some of the most stringent insurance regulations in the U.S.? Yep! If you’re navigating the insurance landscape here, understanding these rules can save you a bundle.
North Carolina’s insurance framework ensures that both consumers and companies play by a fair set of rules. This means rates, practices, and consumer rights are closely monitored to keep the market transparent and competitive.
Key Insurance Regulations in North Carolina
Here’s the deal: North Carolina operates under a “prior approval” system. This means insurance companies need approval from the NC Department of Insurance before changing their rates. Why? To protect you from unjustified rate hikes. These regulations are designed to keep your premiums stable and fair.
Role of the NC Department of Insurance
The NC Department of Insurance isn’t just a regulator; it’s your first line of defense. They scrutinize every rate change proposal to ensure it’s justified. No more surprise charges creeping into your bill without explanation.
Pro Tip: If you feel your rates are unfair, you can file a complaint directly with the NC Department of Insurance.
Impact of State Laws on Insurance Practices
State laws shape the way insurance companies operate in NC. For instance, minimum coverage requirements are defined by state law, ensuring everyone has a financial safety net. BUT, these laws also mean you might pay more if you deviate from the norm.
State laws empower the NC Department of Insurance to enforce compliance, ensuring that all players in the insurance game are following the rules.
Consumer Rights in Insurance
Here’s a quick rundown of what you’re entitled to as an insurance consumer in North Carolina:
- The right to fair and non-discriminatory rates.
- The right to receive a clear and understandable insurance policy.
- The right to file complaints against insurers.
- The right to cancel your policy within a specific period.
- The right to privacy of your personal information.
These rights are designed to empower you as a consumer. Use them wisely!
Future Trends in Insurance Rates in NC
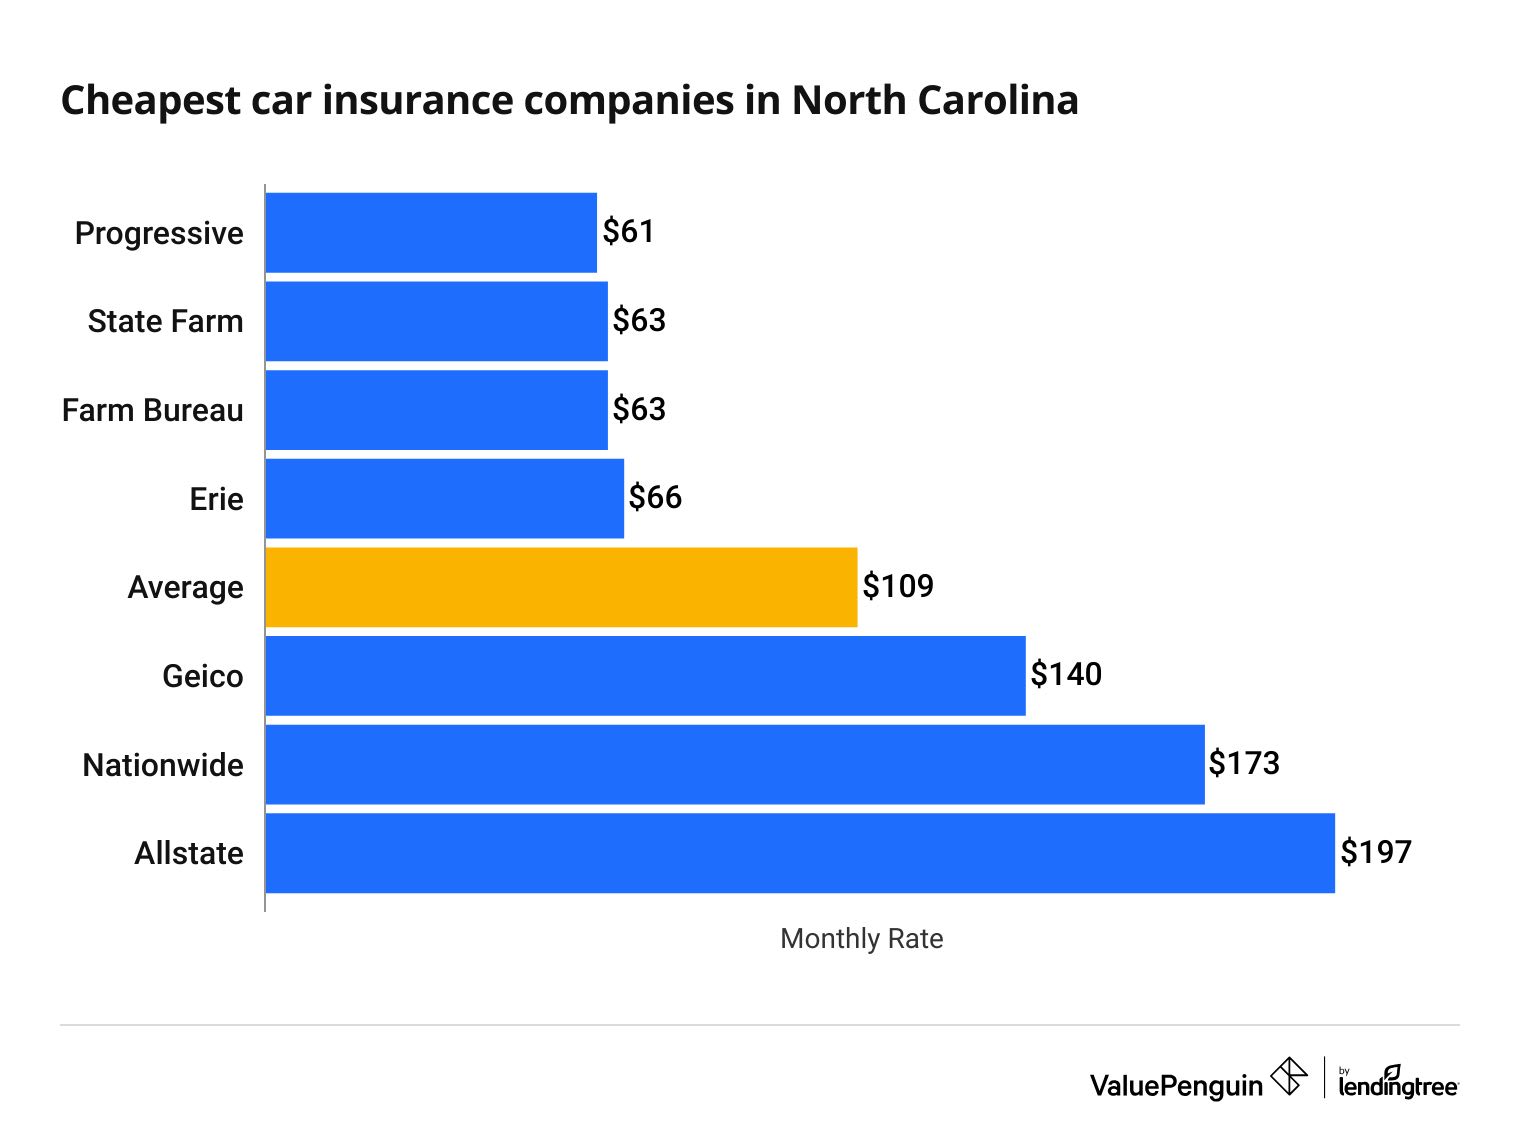
Are you ready to see your insurance premiums rocket or plummet? North Carolina’s insurance rates are set for some radical changes. Let’s dive into the trends shaping the future of insurance in this state.
Technology and regulations are rewriting the insurance playbook in NC. From AI-powered risk assessments to evolving legal frameworks, staying informed is key to keeping costs low.
Impact of Technology on Insurance Pricing in NC
The digital revolution is here, and it’s transforming how insurers calculate your rates. Insurers are now using AI and big data to assess risk more accurately. This means your driving habits and even social media activity could impact your premiums. Scary, right?
Pro Tip: Keep an eye on your digital footprint. A clean online presence might just save you money on your insurance.
Emerging Trends Affecting Future Insurance Rates
Climate change and its impact on natural disasters are also influencing insurance rates. More frequent hurricanes in NC could mean higher costs for home insurance. But, there’s a silver lining. Innovations like usage-based insurance offer personalized rates based on your actual behavior.
- Adopt smart home technology to potentially lower your premiums.
- Consider telematics for your car insurance to benefit from safe driving discounts.
Potential Changes in NC’s Regulatory Environment
Here is the deal: regulatory changes could dramatically alter your rates. The state legislature is considering new laws to make insurance more affordable and transparent. This means possible caps on rate hikes and stricter rules for insurers.
- Stay informed about new insurance bills in North Carolina.
- Leverage consumer protection resources to contest unjust rate increases.
Current vs. Predicted Insurance Rates in NC
Let’s compare the numbers. Below is a forecast table showing how rates might change in the coming years.
| Year | Current Average Rate | Predicted Average Rate |
|---|---|---|
| 2023 | $1,200 | $1,300 |
| 2025 | – | $1,400 |
Final Thoughts
In conclusion, finding the best insurance rates in NC doesn’t have to feel like an uphill battle. By understanding the factors at play, comparing different providers, and keeping an eye on regulatory changes, you can make savvy choices that protect your wallet and your peace of mind. Stay informed, stay proactive, and you’ll be well on your way to securing the best possible insurance rates. Until next time, happy saving!
Frequently Asked Questions
What are the top insurance providers in North Carolina?
Some of the top insurance providers in NC include State Farm, Geico, and Nationwide, each offering a variety of coverage options tailored to residents’ needs.
How can I find affordable insurance rates in NC?
To find affordable rates, consider bundling policies, maintaining a good credit score, and looking for available discounts from various providers.
What factors affect insurance rates in NC?
Insurance rates in NC can be affected by factors such as your location, driving history, and credit score.
How does location impact insurance premiums in NC?
Location can significantly impact premiums, as areas with higher traffic or crime rates generally have higher insurance costs.
What is the difference between full coverage and liability insurance?
Full coverage includes liability, collision, and comprehensive insurance, whereas liability insurance only covers damages to others in an accident.
